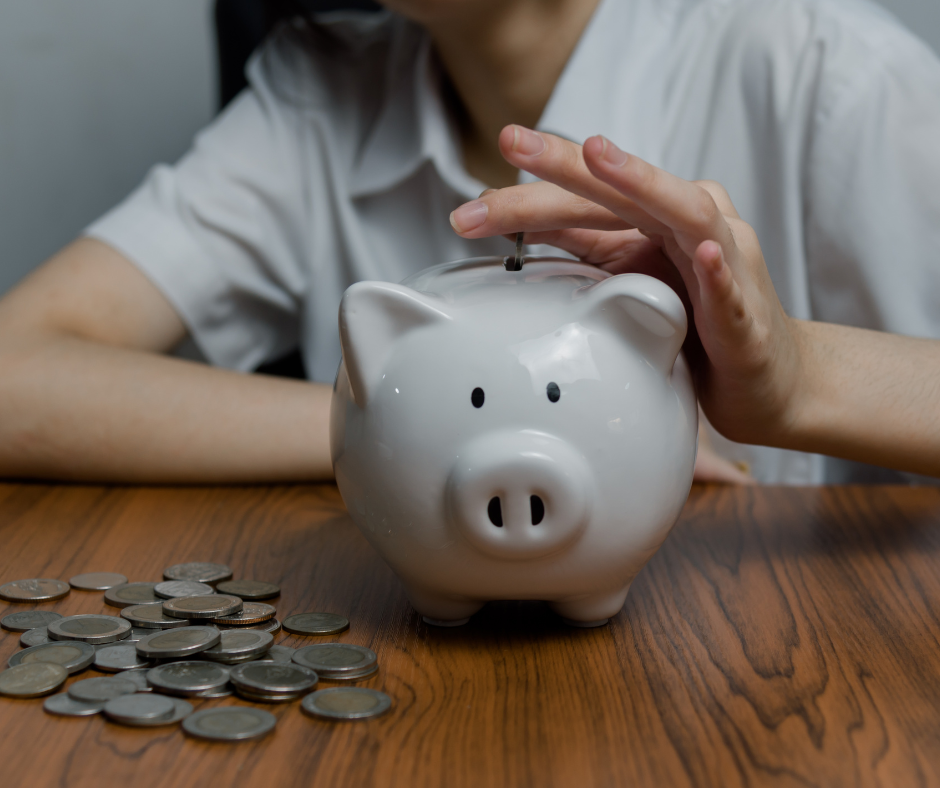
Building wealth is sometimes associated with earning a very high income. In reality, income is only one part of a much broader financial picture that contributes to your wealth.
For Australians earning under $100,000, factors such as spending, debt, savings, superannuation, investment returns and time can all influence longer-term financial outcomes.
Importantly, earning under $100,000 is not unusual. Australian Bureau of Statistics (ABS) data shows median employee earnings were $1,425 per week in August 2025—equivalent to approximately $74,100 a year if received for 52 weeks.
So, what factors might be worth considering when looking to build your wealth position?
1. Knowing the difference between income and spending
Two people earning the same amount can have very different financial outcomes depending on housing costs, family commitments, debt and discretionary spending. Understanding and controlling where household income is going through clear budgeting and agreed spending guidelines can provide a clearer picture of available financial capacity and provide control over what wealth growth is realistically achievable.
2. The impact of time
Long periods can magnify the effect of compounding. As a purely hypothetical illustration, $250 invested each month for 25 years at an assumed average return of 6% a year would grow to approximately $173,000. At 8%, it would be around $238,000. While these figures are mathematical examples only, exclude tax, fees and inflation, and investment returns are not guaranteed, they give you an idea of what wealth growth can be achieved even with a relatively small amount of money with a consistent focus on investing over a long period of time.
3. Superannuation
Having one eye on the future while managing the here and now is a sensible approach to build your long-term wealth. Super can represent a significant component of Australians’ long-term wealth with significant tax incentives available to build your retirement wealth. APRA reported that Australia’s superannuation system held approximately $4.34 trillion in assets at June 2025, while the average account balance across APRA-regulated entities with more than six members was $131,980. APRA also reported a 7.9% annualised rate of return over the five years to June 2025 across those entities.
4. Debt and interest costs
The interest rate, loan term and type of debt can affect how much income is ultimately available for other purposes. Mortgages, credit cards, personal loans and other liabilities all impact your ability to invest and therefore should form an important part of the overall picture of your wealth position.
5. Personal circumstances matter
Age, housing, dependants, employment security, existing assets, access to savings, taxation, future objectives and tolerance for financial risk all affect financial outcomes. Understanding the impact that each of these variables may have on your wealth creation options can give you a realistic view of what is possible and by when.
The point is that, ultimately, wealth is not determined by salary alone.
Looking at income alongside expenditure, liabilities, assets and time can provide a more complete picture of a person’s financial position and help clarify what are realistic goals and long-term outcomes.
This article contains general factual information only. It does not take into account any person’s objectives, financial situation or needs and does not constitute financial, investment, taxation or credit advice.